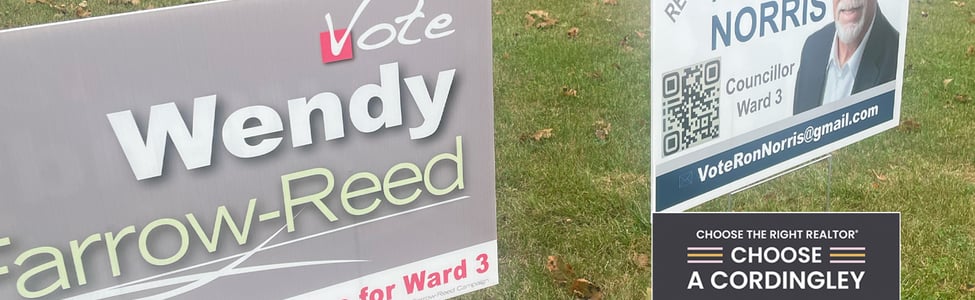
Here are our picks for the two Local Councillor positions representing Ward 3: Wendy Farrow-Reed and Ron Norris.
To be fair, every candidate who puts their name forward deserves credit. Running for public office takes commitment, passion for your community and a genuine willingness to volunteer your time to help make it better.
I won't lie, I seriously considered throwing my own name into the ring for this upcoming election.
A big part of what rekindled that passion was my involvement in opposing the proposed "Monster Build" on Ewing Street. I spent considerable time deep-diving into planning policies and political red tape, researching the existing rules and, ultimately, drafting and submitting our community's formal objection to the Town. An objection based not only on the letter of the existing law, but its intent.
Our argument wasn't that new rules needed to be created. It was much simpler:
The rules and laws already in place needed to be respected and enforced.
Specifically, we relied upon Official Plan Amendment No. 22 and By-law 2017-0032 - the policies already created to protect mature neighbourhoods from overbuilding and ensure new development respects the existing character of the community.
But that submission was only one part of it. Real change started at the grassroots level.
Neighbours stepped up, went door-to-door, kept people informed and rallied behind a common cause. Together, our community delivered 180 handwritten signatures, including a clear majority of residents within the prescribed 60-metre circulation radius.
Ultimately, ours was one of the very few proposals, if not the only one, that did not move forward, with the application halted and deferred through both the Town and Committee of Adjustment process.
A huge win for the community and for the little guys who stood up, got involved and made sure their voices were heard.
For me, the experience was an eye-opener. It demonstrated what can happen when residents understand the rules, get involved and respectfully hold decision-makers accountable to the policies already on the books.
It also made me seriously consider where I might be able to contribute next.
Ron Norris was involved throughout that entire process.He rolled up his sleeves, got his hands dirty and, yes, probably bent a few noses out of shape along the way. He "may have" occasionally pushed the boundaries of his role as Councillor to get us some answers, open channels of communication with the Town and, more importantly, bring those answers back to the people who mattered, the residents, taxpayers and community he represents.
Basically, he reminded me how I operate.
Then a “little bird” told me Wendy Farrow-Reed was considering a return.
After speaking with Wendy directly and learning she would once again be seeking election in Ward 3, my decision became pretty easy. I stepped aside and threw my support behind Wendy Farrow-Reed and Ron Norris, particularly knowing Chantal Garneau would be seeking the Regional Councillor position for Wards 3 & 4.
For residents who have taken the time to attend, participate in or watch Council meetings over this past term, it's been difficult not to notice that Council has often appeared divided into two camps, with one side seemingly working against the other.
I'm hopeful this election provides an opportunity for a more unified Council, one capable of disagreeing when necessary, but ultimately working collaboratively in the best interests of Halton Hills as a whole.
As for me, deciding not to run doesn't mean I've lost interest in getting more involved.
Quite the opposite.
There's a popular idea that it takes roughly 10,000 hours of experience to truly master a craft. Council may technically be considered a "part-time" commitment, however if you look beyond the time spent in Council Chambers. Consider the committees, community events, constituent calls, meetings, preparation and countless volunteer hours that happen outside those chambers.
With a full term under both their belts, Wendy and Ron aren't learning what it means to be Councillors anymore. They've put in the time. They know the job, they know the Town and, most importantly, they know the community.
Following the election, I'm hoping to become more involved with the Town myself, learn from people like Wendy and Ron who have dedicated years to public service, and hopefully put some of my own professional and community experience to work.
One area I'm particularly interested in is the Committee of Adjustment. If an opportunity for nomination or appointment presents itself following the election, I'd welcome the opportunity to serve as a citizen member and bring a practical, professional and community-focused perspective to a process that, in my opinion, could use some modernization and a firm step into 2026.
Sometimes getting involved doesn't mean your name needs to be on the ballot.
Sometimes it means figuring out where you can be most useful and showing up.
And speaking of showing up...
Municipal voting is online this year, so make sure you're registered, sign up and cast your ballot.
If you’re considering buying in Georgetown, Acton within Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
April 9, 2026 - There is a noticeable shift happening across Georgetown and Acton right now. Parking enforcement has become more visible, more consistent, and for many homeowners, more frustrating. A bumper slightly over the sidewalk, a vehicle extending into what feels like your own driveway, and suddenly there is a ticket.
It feels minor. It feels technical. It feels unnecessary.
The reaction is predictable.
If the issue is space, then create more of it. Widen the driveway. Add another parking spot. Adjust the layout so the property works better.
On its face, that reasoning feels practical. It feels like a small correction to an inconvenient rule.
It is not.
What sits behind that decision is an assumption, and it is the same assumption that continues to surface across Ontario real estate. If a change is limited, logical, and improves how a property functions, it should be allowed.
That assumption is not supported by how zoning works.
The point where this becomes clear is not in theory. It is in how these situations are actually decided.
In Singh v Cambridge (City), 2026 CanLII 30974 (ONLT), the issue was not dramatically different from what many homeowners across Georgetown and Acton are considering right now. The property owner sought to expand driveway coverage and reduce landscaped open space to support additional parking tied to a residential use. The proposal was not extreme. It did not attempt to fundamentally change the property. It was, in practical terms, an adjustment intended to make the property function better.
That was not enough.
The Ontario Land Tribunal did not assess whether the change was useful, or whether it aligned with how the property was being used in reality. It assessed whether the proposal maintained the intent and purpose of the zoning by-law.
It did not.
The application was refused.
There were no damages awarded, no extended dispute, and no further negotiation of the outcome. The proposal failed to meet one of the required tests under the Planning Act, and that was sufficient to end the analysis. The use could not proceed. The change was not permitted. The property remained subject to the existing zoning framework, unchanged.
That is how these situations typically resolve.
Not through argument, and not through interpretation, but through compliance.
What often gets overlooked is what that actually means for the person on the other side of that decision.
In Singh v Cambridge (City), 2026 CanLII 30974 (ONLT), the outcome was not just a refused application. It was time, cost, and effort that did not translate into a usable result. The process itself requires applications, supporting materials, and a hearing. It requires time to prepare, time to wait, and time to see the decision through.
And when the decision is refusal, the impact is not neutral.
The proposed use cannot proceed. Plans tied to that use are effectively blocked. The property must comply with the existing zoning framework, or the owner must attempt a new application with no guarantee of success.
There are no damages awarded to offset that outcome.
But the financial impact is real.
Costs associated with planning, applications, and any work undertaken in anticipation of approval remain with the owner. If changes were made that do not comply, they may need to be removed or reversed. Any anticipated use, whether tied to rental income or expanded functionality, is lost.
This case confirms that zoning is enforced strictly, and intended use does not override compliance. A property that appears suitable for additional use or modification may still be refused if it does not meet zoning requirements.
The result is a property that cannot be used as intended, with financial consequences that are not recoverable through the Tribunal process.
What makes this particularly relevant right now is that the current parking frustrations being experienced across Georgetown and Acton are not separate from this framework. They are part of it. When a vehicle no longer fits within the permitted space, enforcement becomes visible. That visibility is often interpreted as the problem.
It is not.
It is the point where the property is already operating at, or beyond, what is permitted.
The risk begins when the response shifts from adjusting behaviour to altering the property itself without confirming whether that alteration is allowed.
That shift moves the issue out of parking and directly into zoning.
From there, the outcome becomes far more predictable.
If the proposed change complies, it may be approved. If it does not, it will not. Whether the change is minor, whether it improves usability, or whether similar conditions exist elsewhere does not alter that analysis.
This is the pattern that continues to show up in real transactions. Properties are often evaluated based on how they appear to function. There seems to be enough space. There seems to be flexibility. There seems to be potential. But when zoning is reviewed properly, those assumptions are not always supported.
There are situations where additional parking cannot be recognized. Where driveway expansions are restricted. Where a property that appears to support a secondary use does not meet the requirements to do so.
At that point, there are no creative solutions. There is only the framework that already exists.
The decision becomes whether to proceed within those limits, seek approval with no certainty, or step away.
Zoning determines what is permitted. It does not adjust to what would make a property more functional.
Once that line is understood, the context around parking, driveway changes, and property use becomes much clearer. The issue is not whether something can be done physically. It is whether it is allowed legally.
That distinction is where most exposure begins, and where most of it can be avoided.
If there is a single takeaway, it is this.
Zoning determines what you are allowed to do with a property, not what you believe you can do, and once a use is refused, the cost of that assumption is yours to carry.
Additional Resources: Parking & Boulevard Rules in Halton Hills
For homeowners across Georgetown and Acton dealing with parking constraints, the Town of Halton Hills outlines clear rules that are actively enforced.
Vehicles are not permitted to park on or overhang a sidewalk. The portion of a driveway between the sidewalk and the road is considered part of the municipal right-of-way. Vehicles must be fully contained on the permitted hard surface, and parking on landscaped portions of the boulevard is not allowed. Even minor overhangs can result in enforcement.
If you’re considering buying in Georgetown, Acton within Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
The case confirms what is often overlooked in practice. A mutual release is not a single, unified release of all obligations. It is a combined document operating on separate legal tracks.
The first track governs the relationship between buyer and seller. It brings the Agreement of Purchase and Sale to an end, releases the parties from claims against each other, and directs how the deposit will be disbursed. Once both parties sign, that portion is effective. The brokerage is not required to sign for that release to take effect.
The second track governs commission.
A brokerage only releases its entitlement to commission if it signs the portion of the document that expressly provides for that release. If the brokerage does not sign, it has not waived its rights. The transaction may be over, the deposit may be resolved, and yet commission exposure may still exist.
This distinction is not theoretical. It was determinative in the Khanna decision.
When the Deal Ends but the Obligation Remains
In Khanna, the sellers chose not to complete a firm transaction. A buyer had been secured who was ready, willing, and able to close. The failure of the deal was attributed to the sellers.
A mutual release was signed between the buyer and seller.
The sellers took the position that the release ended all obligations, including commission.
The court rejected that position.
The listing brokerage had not signed the commission release portion of the document. As a result, it had not agreed to waive its entitlement. The court enforced the commission clause contained in the listing agreement.
The result is consistent with Ontario contract law. Commission rights arise from the listing agreement and, depending on its wording, may survive a failed closing where the failure is attributable to the seller.
A mutual release does not override that contractual framework unless it expressly does so.
Commission Entitlement Does Not Remove Fiduciary Duty
The Khanna decision did not end with commission being awarded. It addressed how that commission was claimed.
The brokerage invoiced for the full commission amount, including the portion attributable to the cooperating brokerage. That portion had already been released.
The court found that conduct to be a breach of fiduciary duty.
Even where commission is owed, it must be enforced honestly and in accordance with the actual contractual entitlement. The court reduced the award by $10,000 as a penalty for overreaching.
The distinction matters. Commission entitlement and fiduciary conduct are not the same issue. A brokerage may be entitled to be paid and still be penalized for how it pursues that payment.
Where Most Disputes Actually Begin
The court’s reasoning highlights a recurring problem in failed transactions. The issue is not always the contract itself. It is often the absence of clarity.
In Khanna, the outcome turned heavily on credibility. The court accepted that the sellers had been verbally warned that commission remained payable. There was no clear written confirmation at the time the mutual release was being discussed.
The court noted that a single written sentence confirming that commission remained owing would likely have avoided the dispute entirely.
In Ontario real estate, where timelines are compressed and decisions are made quickly, that absence of written clarity is common. It is also avoidable.
Where the transaction is being brought to an end, the analysis returns to the mutual release.
Each document performs a different legal function. Confusing those functions is where exposure begins.
Local Context Does Not Change Legal Structure
Across Georgetown and Acton in Halton Hills, and in surrounding rural markets such as Erin in Wellington County, the triggers for mutual releases vary.
Financing timelines may not align. Inspections may uncover issues that cannot be resolved. Insurance or underwriting approvals may introduce delays. In firm transactions, closing risks may surface late in the process.
The reasons differ. The legal structure does not.
The agreement ends only when it is properly documented. The deposit is only disbursed when the direction is clear. The scope of what is released depends entirely on the wording of the document and the parties who have agreed to it.
Barry Cordingley and Tracy Cordingley approach mutual releases as settlement instruments, not administrative forms.
The objective is not to secure a signature for the sake of moving a file forward. The objective is to ensure that the document reflects the actual resolution between the parties, that the deposit instructions can be relied upon, and that any continuing obligations are clearly understood.
The Khanna decision reinforces that approach.
A mutual release can end a transaction cleanly. It can also leave obligations in place where those obligations have not been expressly addressed.
The difference is not in the form itself. It is in how it is understood, structured, and executed.
The Principle That Carries Forward
Contractual rights, financial obligations, and settlement documents must each be reviewed on their own terms, not assumed to operate as a single outcome.
Let’s Continue the Conversation
If you’re considering buying in Georgetown, Acton within Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
Ontario has announced a significant housing policy shift, extending and enhancing the HST rebate on new homes in an effort to stimulate construction and improve affordability across the province.
The announcement, made by Premier Doug Ford on March 25, 2026, introduces a temporary but meaningful change. For a defined period, the province plans to effectively remove the 13 percent HST on new homes valued up to $1 million, with the program expected to run from April 1, 2026 through March 31, 2027. Read the official Ontario government announcement.
While framed as a rebate extension, the practical effect is closer to a full tax exemption within that price range.
A Reset on New Construction Affordability
Ontario’s housing market has faced sustained pressure, not only from demand, but from the cost of building itself. Taxes, development charges, and construction inputs have all contributed to elevated pricing.
By extending the HST rebate to effectively eliminate the tax on qualifying new homes, the province is targeting one of the few levers it can directly control.
For buyers, this creates a rare window where newly built homes may compete more directly with resale inventory on price, something that has not been consistently true in recent years.
For builders, it introduces an incentive to move projects forward that may have previously been paused or reconsidered.
What This Means in Practical Terms
For a new home priced at $1,000,000, a full 13 percent HST exemption represents a potential savings of $130,000.
That is not a marginal adjustment. It is a structural shift in how new construction is priced relative to resale.
However, the impact will not be uniform.
Some of the rebate may be absorbed into pricing as builders respond to demand. Some may be passed through directly to buyers. In many cases, the result will land somewhere in between.
The key point is not that every buyer will save the full amount, but that the pricing relationship between new and resale homes is being recalibrated.
Buyers comparing options should also understand how this interacts with Due Diligence, Risk & Property Verification, particularly when evaluating new construction timelines, builder agreements, and occupancy structures.
Implications for Georgetown, Acton, and Erin
In markets like Georgetown and Acton in Halton Hills, and Erin in Wellington County, this policy intersects with a very specific local dynamic.
Outside of Erin, these are communities where new construction exists, but is often limited relative to resale inventory.
The extended HST rebate may influence that comparison more directly than before.
A buyer weighing a newer resale home versus a pre-construction or recently built property may now find the gap narrower, particularly within the sub-$1M range.
This is especially relevant for buyers evaluating:
Barry Cordingley and Tracy Cordingley have consistently observed that buyers are not strictly choosing between “new” and “resale”, they are choosing between risk profiles, timelines, and long-term flexibility. This policy directly affects that decision framework.
The rebate applies to new construction, not resale. But markets don’t operate in isolation. When new homes become more competitive, buyers recalibrate.And that shift works its way through resale pricing, strategy, and outcomes across Halton Hills and Wellington County.
A Short-Term Policy With Long-Term Effects
It is important to recognize that this is a time-limited program, currently expected to run for one year.
Policies like this tend to pull forward demand.
Buyers who were planning to act in 2027 or later may now accelerate their timelines to take advantage of the rebate window. Builders may also adjust release schedules accordingly.
This creates a potential compression effect:
Increased activity in the short term
Possible slowdown once the incentive expires
Understanding that cycle is critical when advising on timing.
Not Just a Buyer Story
While the headline focuses on buyers, the broader intention is to support housing supply.
If it succeeds in doing so, the real impact may not be immediate price relief, but increased inventory over time.
Where This Fits in the Current Market
This announcement arrives at a moment when many Ontario markets, including Halton Hills, have already experienced price adjustments from peak levels.
In that context, the extended HST rebate does not operate in isolation. It interacts with:
Current pricing corrections
Interest rate expectations
Buyer sentiment and confidence
Available resale inventory
For buyers navigating this environment, understanding the Guide to Buying with Confidenceprovides a structured way to evaluate decisions beyond surface-level pricing changes.
The Takeaway
The extension of the HST rebate on new homes is not just a tax change. It is a policy designed to influence behavior.
It reshapes how buyers compare options.
It changes how builders price and release inventory.
And it introduces a defined window where timing becomes part of the strategy.
For buyers and sellers in Georgetown, Acton, and Erin, the question is not simply whether this is positive or negative.
The question is how it affects the specific property, price range, and decision in front of them.
Let’s Continue the Conversation
If you’re considering buying in Georgetown, Acton within Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
March 24, 2026 - Work is now underway at the Acton Wastewater Treatment Plant, and for most residents, it will register first as movement rather than meaning.
There will be trucks. There will be periods of noise. There will be a visible contractor presence near the facility.
What sits behind that activity is more consequential.
Project PR-3417A is a Halton Region infrastructure upgrade scheduled from March 2026 through August 2027, tied to maintaining the plant in a state of good repair while modernizing how it operates internally. The work is taking place within the existing facility in Acton, Halton Hills, Ward 1, with construction carried out by Mega Group Construction Limited and engineering oversight by Associated Engineering Limited.
The project itself is not speculative. It aligns with previously awarded regional procurement tied to plant upgrades, as confirmed through Halton Region tender S-3417A-25, with a construction duration consistent with the current timeline.
Administration Building Upgrades. Acton Wastewater Treatment Plant WARD1, In The Town Of Halton Hills (Acton) PR-3417A
The scope is focused and practical.
Digital network and control room upgrades will modernize how the plant is monitored and operated. Major building maintenance, including roof, HVAC, and window replacements, addresses core structural and operational needs. Administrative areas are being renovated to support staff functionality, including meeting space, lunchroom, and change facilities.
This is not expansion. It is reinforcement.
The budget reflects that level of work. Industry reporting places the project within a range of approximately one to five million dollars, consistent with mid-scale municipal upgrades, as reflected through Canadian construction tender reporting.
Acton Wastewater Treatment Plant in Halton Hills, ON
For residents, the immediate impact is limited but real.
Those closest to the plant will experience intermittent construction noise and increased truck traffic during the project window. Work will be scheduled within local by-laws, but activity will still be noticeable at times. For the broader Acton community, the project will remain largely in the background, present, but not intrusive.
What matters more is why this work is happening at all.
Wastewater infrastructure is one of the least visible, but most critical, systems supporting any community. It determines how reliably services are delivered, how environmental standards are maintained, and how much demand the system can handle over time.
This is not reactive work. It is planned infrastructure renewal tied to both current needs and future demand.
For residents, that translates into stability.
Systems are being updated before they fail. Operational reliability is being reinforced. Environmental compliance is being maintained at current standards. The plant continues to function as intended, without interruption, without degradation, and without placing strain on surrounding systems.
Over time, this type of work has a broader effect.
Wastewater capacity is one of the primary constraints on growth. When it is maintained and modernized, it supports the municipality’s ability to accommodate change, whether that comes through new housing, incremental density, or evolving land use.
That shift is gradual. It is not immediate, and it is not always visible.
But it is foundational.
For buyers reviewing Homes for Sale in Acton, these factors sit quietly beneath the surface of every decision. Infrastructure is rarely discussed directly, but it informs confidence in the community, its services, and its long-term reliability.
A community that continues to invest in its infrastructure tends to remain stable, predictable, and supported. That consistency becomes part of how value is interpreted, particularly in markets where buyers are increasingly attentive to long-term fundamentals.
Acton does not exist in isolation within that conversation.
Buyers rarely discuss infrastructure directly, but it sits behind how communities are compared. Differences in servicing capacity, reliability, and long-term planning quietly influence where people choose to buy.
That is where this project carries its real significance.
PR-3417A is not designed to change how Acton looks.
It is designed to ensure that Acton continues to function properly, quietly, and reliably, as it moves forward.
For residents, the experience will be temporary construction followed by very little visible change.
Underneath that, the systems supporting the community will be stronger, more modern, and better prepared for what comes next.
Let’s Continue the Conversation
If you’re considering buying in Georgetown, Acton within Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
March 18, 2026 - The latest decision from the Bank of Canada arrives at a moment where the signal matters more than the move itself. Rate changes tend to capture attention, but the underlying conditions shaping those decisions are where the real implications sit.
February introduced a notable shift. Canada’s economy shed 84,000 jobs, the sharpest monthly contraction in four years, while unemployment moved to 6.7%. It is the kind of data that does not immediately alter behaviour, but it changes tone. Hiring pauses. Expansion plans are reconsidered. Households begin to weigh decisions more carefully, particularly those tied to long-term commitments.
Inflation, as reflected through the Consumer Price Index, has been moving closer to the Bank’s target range, though not in a straight line. The trajectory has softened, but it remains uneven beneath the surface. That leaves policymakers navigating a narrow path between two forces that rarely align neatly: a cooling labour market and inflation that has not fully settled.
Mortgage markets tend to move slightly ahead of the Bank of Canada, not in lockstep with it. Fixed rates are influenced more directly by bond yields, which have already begun adjusting to softer economic data and easing inflation expectations. As a result, some lenders have quietly reduced fixed-rate offerings even without a formal rate cut. Variable-rate products, by contrast, remain tied to the Bank’s overnight rate and will only adjust once policy shifts occur. The practical effect is a narrowing gap between fixed and variable options, creating a more nuanced decision point for borrowers. In this environment, mortgage strategy becomes less about predicting the next announcement and more about aligning structure with time horizon, risk tolerance, and intended holding period.
A shifting rate environment begins to reshape the housing market, as economic signals and real estate fundamentals move back into alignment across Ontario.
In Ontario’s real estate markets, and more specifically across Georgetown, Acton, and Erin, the translation of those forces is rarely immediate, and never identical to what unfolds in larger urban centres. What tends to surface first is not price movement, but posture. Buyers become more deliberate. Sellers grow more aware of positioning. Transactions continue, though the pace and tone shift.
There is a noticeable absence of urgency in current negotiations. Not hesitation, but restraint. Offers are constructed with greater precision. Conditions, once dismissed outright in more aggressive cycles, are returning in measured form. The result is a market that feels quieter on the surface, though no less active beneath it.
Within this environment, pricing has become less about momentum and more about alignment. Homes that enter the market with a clear understanding of recent comparable sales continue to trade. Those that rely on aspirational positioning tend to linger, not indefinitely, but long enough to recalibrate expectations.
This is where the distinction between asking price and achieved value becomes increasingly relevant. Public-facing listings offer only a partial view. The substance of the market is found in what has actually transacted.
Real-time, verified sold prices across Georgetown, Acton, and Erinprovide a clearer measure of where buyers are willing to engage today, not where sellers hoped to be yesterday.
The Bank of Canada’s forward posture now carries greater weight than any single announcement. Should policy begin to ease later in the year, the response is unlikely to be gradual. There is a measurable level of deferred demand, particularly among buyers who have remained financially capable but strategically patient. When confidence returns, it tends to do so quickly.
Conversely, if rates remain elevated for longer than anticipated, the current equilibrium holds. Transactions continue. Supply remains controlled. Price movement, where it occurs, is incremental rather than abrupt.
Local dynamics continue to provide a degree of insulation. Halton Hills and Wellington County do not operate with the same volatility as more densely concentrated markets. Housing stock remains limited relative to demand. The preference for ground-oriented housing persists. Migration patterns from the broader GTA continue to support absorption, even as broader economic indicators soften.
None of this suggests immunity. It suggests resilience.
In this phase of the cycle, outcomes are increasingly tied to execution rather than conditions alone. Buyers who understand where value is actually clearing are able to move with a level of confidence that is not dependent on perfect timing. Sellers who approach the market with precision rather than optimism continue to find traction.
There is a tendency to look to central bank decisions for clarity. In practice, clarity is rarely delivered in that form. It emerges gradually, through pricing, through negotiation, and through the cumulative effect of transactions that define the market more accurately than any announcement.
The present environment does not reward reaction. It favours discipline.
Barry and Tracy Cordingleycontinue to operate within that framework across Georgetown, Acton, and Erin, where interpretation of the market carries as much weight as participation in it.
Let’s Continue the Conversation
If you’re considering buying in Georgetown, Acton within Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
February 17, 2026 - Canada’s annual inflation rate edged down to 2.3 per cent in January, helped largely by a decline in gasoline prices. The latest figures from Statistics Canada show a modest cooling rather than a dramatic shift, but in financial markets and in real estate modest shifts tend to matter.
Gas prices are one of the most visible components of inflation. When they fall, households notice immediately. In communities like Georgetown and Acton in Halton Hills, and throughout Erin in Wellington County, where driving is part of daily routine, fuel costs are not abstract line items. They are part of monthly math. A little breathing room changes sentiment.
A winter scene in suburban Ontario reflects January’s cooling inflation rate of 2.3%, as declining gas prices ease household pressure and support stability in the real estate markets of Georgetown and Acton in Halton Hills, and Erin in Wellington County.
Sentiment influences decisions.
Inflation remains closely watched by the Bank of Canada because it directly informs interest rate policy. While core measures still guide long-term direction, a headline rate moving closer to target reduces the pressure for further tightening. Stability, even incremental stability, begins restoring confidence in borrowing conditions.
For Ontario real estate, that confidence is significant. Buyers respond to predictability more than to optimism. When rate volatility subsides, financing conversations become clearer. Sellers see fewer hesitant offers and more structured ones. Markets function best when participants understand the cost of capital with reasonable certainty.
Barry Cordingley and Tracy Cordingley regularly remind clients that inflation is not simply an economic statistic it shapes the lending environment within which every Agreement of Purchase and Sale is negotiated. In Halton Hills and Wellington County, local inventory and property fundamentals always lead, but borrowing conditions frame the tempo of activity.
A 2.3 per cent reading does not create urgency. It reduces friction.
Detached homes in Erin, established properties in Georgetown, and newer builds in Acton will not move because of a single CPI report. Yet sustained moderation supports stability in mortgage pricing, and stability supports transaction depth. That depth quietly sustains values.
The present environment feels measured rather than volatile. Inflation is not accelerating in a way that destabilizes households, nor has it fully returned to long-term equilibrium. Markets adjust gradually in this range. Buyers who paused during sharper inflation cycles often re-enter once conditions feel less uncertain. Sellers regain confidence that financing approvals will hold through to registration and closing.
Economic releases are considered within the context of disciplined execution. Macro trends inform strategy. They do not replace it.
January’s inflation figure suggests moderation, not momentum. In real estate, moderation is often where durable decisions are made.
Let’s Continue the Conversation
If you’re considering buying in Georgetown, Acton within Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
January 28, 2026 - Today, the Bank of Canada announced that it would hold its benchmark interest rate, choosing not to raise or lower borrowing costs at this time. While no change was made, the tone of the announcement was just as important as the decision itself—measured, cautious, and deliberately steady.
For homebuyers, this type of messaging matters.
A Message of Stability, Not Celebration
The Bank’s communication was not overly optimistic, nor was it alarmist. Instead, it reinforced that inflation is being monitored closely, economic growth remains uneven, and global uncertainty continues to influence decision-making. The takeaway for buyers is not that rate cuts are imminent, but that policymakers are comfortable enough with current conditions to pause and observe rather than react.
This “wait-and-see” tone signals that the Bank is attempting to balance inflation control with economic stability, avoiding abrupt moves that could unsettle households or financial markets.
Stability comes at a cost.
As interest rates hold, Canadian households continue to carry the weight of higher living and borrowing costs.
What a Rate Hold Means If You’re Buying a Home
For buyers actively searching—or preparing to start—in communities like Georgetown, Acton, and Erin, today’s decision provides a short-term sense of predictability. Variable mortgage rates are unlikely to change as a direct result of this announcement, and lenders now have clearer footing when issuing pre-approvals and rate holds.
Fixed mortgage rates are influenced more by bond markets than by the overnight rate itself, but a steady central bank often helps limit sharp swings in those markets as well. In practical terms, this environment allows buyers to plan with more confidence around monthly affordability, down payment strategy, and timing.
Why the Tone Matters More Than the Headline
While “no rate change” may sound uneventful, the Bank’s tone suggests it is being deliberately patient. There was no urgency to tighten further, but no commitment to easing either. For buyers, this reinforces the importance of preparation rather than speculation.
Rather than waiting for a perfect rate environment that may or may not arrive, well-prepared buyers focus on fundamentals: mortgage structure, budget comfort, neighbourhood selection, and long-term suitability of the home.
How Buyers Can Use This Moment Strategically
In a steady-rate environment, buyers often have more room to negotiate thoughtfully and make decisions without the pressure of sudden borrowing cost changes. This is especially relevant in balanced or slower-moving local markets, where pricing, conditions, and closing timelines can matter just as much as interest rates.
Barry Cordingley and Tracy Cordingley regularly advise buyers that successful home purchasing is rarely about timing the market perfectly. Instead, it’s about understanding today’s conditions, structuring financing conservatively, and choosing a home that supports both lifestyle and long-term plans.
The Bottom Line for Buyers
Today’s Bank of Canada announcement reinforces a message of caution and stability. Rates are being held because the system is still adjusting, not because risks have disappeared. For buyers, this creates an environment where preparation, clarity, and local expertise matter more than guessing where rates might go next.
For those considering a purchase in Georgetown, Acton, or Erin, now is a time to focus on readiness—knowing your numbers, understanding your options, and working with professionals who can help you navigate both the financial and practical sides of buying with confidence.
Let’s Continue the Conversation
If you’re considering buying in Georgetown, Actonwithin Halton Hills, or Erin within Wellington County we’re here to help you move forward with clarity and confidence.
Because who you choose matters.
📣 CHOOSE THE RIGHT REALTOR® | CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
December 31, 2025 - As longtime Georgetown and Acton real estate professionals, we know that homeowners care about more than just market conditions — they care about how their community works day to day. From schools and infrastructure to services like waste and recycling, these details matter when you live, invest, and build roots in Halton Hills.
With changes coming to the Blue Box recycling program in 2026, many residents are asking: What’s changing? What stays the same? And how does this affect my household?
Here’s a clear, straightforward guide for Georgetown and Acton residents.
What Is Changing With the Blue Box Program in Halton Hills
Beginning January 1, 2026, the responsibility for residential Blue Box recycling in Halton Hills will shift from Halton Region to a province-wide organization called Circular Materials Ontario.
This change is part of Ontario’s Extended Producer Responsibility (EPR) framework. Under this system, the companies that produce packaging and printed paper are responsible for funding and managing recycling programs — rather than municipalities.
Halton Hills (including Georgetown and Acton) will now be part of a standardized, Ontario-wide recycling system.
When the Recycling Changes Take Effect
📅 Effective date:January 1, 2026
From that date forward:
Circular Materials Ontario oversees the Blue Box program
Recycling collection and customer service are managed through Circular Materials’ designated service partners
Halton Region continues managing garbage, Green Cart, yard waste, and bulk waste
The most important takeaway for homeowners is that daily routines won’t be disrupted.
✅ Your recycling pickup day stays the same Whether you live in Georgetown, Acton, or a rural part of Halton Hills, your scheduled collection day does not change.
✅ You keep using your existing Blue Box or clear recycling bags No new containers are required unless yours becomes damaged or lost.
✅ Garbage and Green Cart programs are unchanged These services remain under Halton Region’s management.
In short — your recycling still goes to the curb on the same day, in the same way.
What’s New Under Circular Materials Ontario
While collection feels the same, how the program is managed behind the scenes changes.
Province-wide Recycling Standards
One of the biggest improvements is a standardized recycling list across Ontario. This helps reduce confusion about what belongs in the Blue Box and makes recycling rules more consistent no matter where you live.
Commonly accepted materials include:
Paper and cardboard (newspapers, flyers, cereal boxes)
Plastic containers and bottles
Metal food and beverage cans
Glass bottles and jars
Accepted materials may expand over time as the program evolves.
New Customer Service Model
After January 1, 2026:
Missed recycling pickups
Damaged or missing Blue Boxes
Questions about recycling materials
…will be handled through Circular Materials Ontario’s customer service system and its local collection partner (currently Miller Waste in Halton).
How the Changes Impact Halton Hills Homeowners
For residents of Georgetown and Acton, the impact is largely positive:
✔️ No schedule disruptions ✔️ Clearer recycling rules ✔️ More consistent guidance across Ontario ✔️ Less confusion when moving or comparing programs between municipalities
From a broader perspective, the shift helps modernize recycling while easing cost pressures on municipalities — helping communities like Halton Hills remain sustainable and well-managed over the long term.
Frequently Asked Questions
Will my recycling pickup day change in Georgetown or Acton? No. Your current pickup schedule remains the same after January 1, 2026.
Do I need a new Blue Box? No. Existing Blue Boxes and clear recycling bags will continue to be used.
Who do I contact for recycling issues after 2026? Recycling questions and service issues will be handled through Circular Materials Ontario’s customer service system.
Is Halton Region still involved? Yes — Halton Region continues managing garbage, Green Cart, yard waste, and bulk waste programs.
Why Community Knowledge Matters
Understanding changes like these is part of being an informed homeowner — and it’s also part of choosing the right professional when buying or selling real estate.
Communities aren’t just homes and streets; they’re systems that need to work well together. Staying informed helps protect property values, quality of life, and long-term planning decisions.
Final Thought
For Georgetown and Acton residents, the 2026 Blue Box transition brings clarity and consistency with minimal disruption. You’ll keep recycling the same way, on the same day — with the added benefit of a simpler, province-wide system.
📣 CHOOSE THE RIGHT REALTOR®; CHOOSE A CORDINGLEY Because who you choose changes everything. — Barry & Tracy Cordingley
December 10, 2025 — In its final scheduled monetary policy decision of the year, the Bank of Canada (BoC)announced on Wednesday that it will hold its target for the overnight policy interest rate at 2.25%, where it has stood since an October rate cut. The Bank Rate remains at 2.50% and the deposit rate at 2.20%.
The decision to pause monetary policy tightening was widely expected by economists and financial markets, capping a year marked by multiple rate reductions aimed at supporting economic activity amid ongoing inflation pressures and global uncertainties.
Why the BoC Held Rates
According to the BoC’s official press release, Governing Council assessed that keeping the policy rate at 2.25% is appropriate at this stage to achieve its inflation target while allowing the Canadian economy to adjust through structural shifts, particularly those related to trade conditions.
Although headline inflation has moderated — with consumer price index (CPI) inflation slowing to around 2.2% in October and remaining close to the Bank’s 2% objective — underlying price pressures have been more persistent, especially in core measures of inflation. \
Moreover, economic data present a mixed picture:
Canada’s real gross domestic product (GDP) grew a robust 2.6% annualized in the third quarter, but the Bank projects weaker growth in the fourth quarter due to slowing exports and ongoing trade volatility.
The labour market has gradually improved, with recent solid employment gains and a lower unemployment rate, though hiring intentions and demand in trade-sensitive sectors remain subdued.
BoC Governor Tiff Macklem reiterated that while the economy has shown resilience, elevated uncertainty — particularly around global trade relations and tariff pressures — still warrants a cautious approach.
Market Reaction and Outlook
Financial markets reacted calmly to the hold. The Canadian dollar edged slightly higher against the U.S. dollar, reflecting continued confidence in Canada’s economic prospects, even as bond yields softened.
Economists broadly expect that the Bank will keep rates on hold into the first half of 2026, with some speculating that the next meaningful move could be a rate increase later in the year, should inflation and employment dynamics evolve more strongly than anticipated.
What This Means for Canadians
For households and borrowers, the decision provides a measure of stability in borrowing costs, especially for those with variable-rate mortgages or lines of credit tied to the policy rate. Lower-income households and consumers may also benefit from a more predictable interest rate environment as they plan budgets and manage debt.
For businesses, especially in trade-exposed sectors, the pause offers time to adjust to competitive pressures and shifting global demand without the added strain of higher borrowing costs. However, caution remains due to external risks such as U.S. trade policy and global market fluctuations.
Looking Ahead
The next Bank of Canada policy rate announcement is scheduled for January 28, 2026, when the Bank will reassess emerging economic data, including inflation trends, labour market conditions, and international developments.
In the meantime, analysts and investors will be closely watching economic indicators for signs of whether the Bank is shifting toward a prolonged pause or preparing for future rate adjustments.
📣 CHOOSE THE RIGHT REALTOR®; CHOOSE A CORDINGLEY
Because who you choose changes everything.
BUY, SELL & #CHOOSEACORDINGLEY — Barry & Tracy Cordingley